


In January, gold briefly traded above $5,500 an ounce. It capped one of the most powerful rallies any major asset has produced this decade, after a 2025 in which the metal gained nearly 65%. The gold price today tells a very different story.
This week, gold finished around $4,280. That is more than 20% below the peak, and the metal has now fallen for a second straight month.
Gold now sits at a genuinely interesting crossroads. On one side, record bond yields and a hawkish Federal Reserve are pulling it down. On the other, central banks keep buying, geopolitical risk remains elevated and several of Wall Street’s largest banks still expect prices to climb before the year is out. Understanding why gold is caught between those forces is the key to reading where it goes next.
Where the gold price today stands
Gold rose to $4,293.06 an ounce on 25 September, up 0.43% on the day. However, it remained down more than 1% for the week, 6.55% lower over the past month and still almost 14% higher than a year ago.
That combination tells the story. In the short term, gold is under pressure. Over a longer horizon, it remains one of the best-performing assets of the past two years.
Late on Friday in New York, spot gold was bid at about $4,284 an ounce, with the day’s range spanning roughly $4,254 to $4,317. The move was limited because two opposing forces were at work at once: falling oil prices and ongoing geopolitical uncertainty offered support, while elevated Treasury yields and firm expectations of further Fed tightening capped gains.
Why rising yields hurt gold
To understand gold’s recent weakness, you need to understand one concept: opportunity cost.
Gold pays no interest and no dividend. Its return comes entirely from price appreciation. When interest rates are low, that does not matter much, because cash and bonds pay very little anyway. When rates rise sharply, investors can earn a meaningful, virtually risk-free return by holding Treasuries instead.
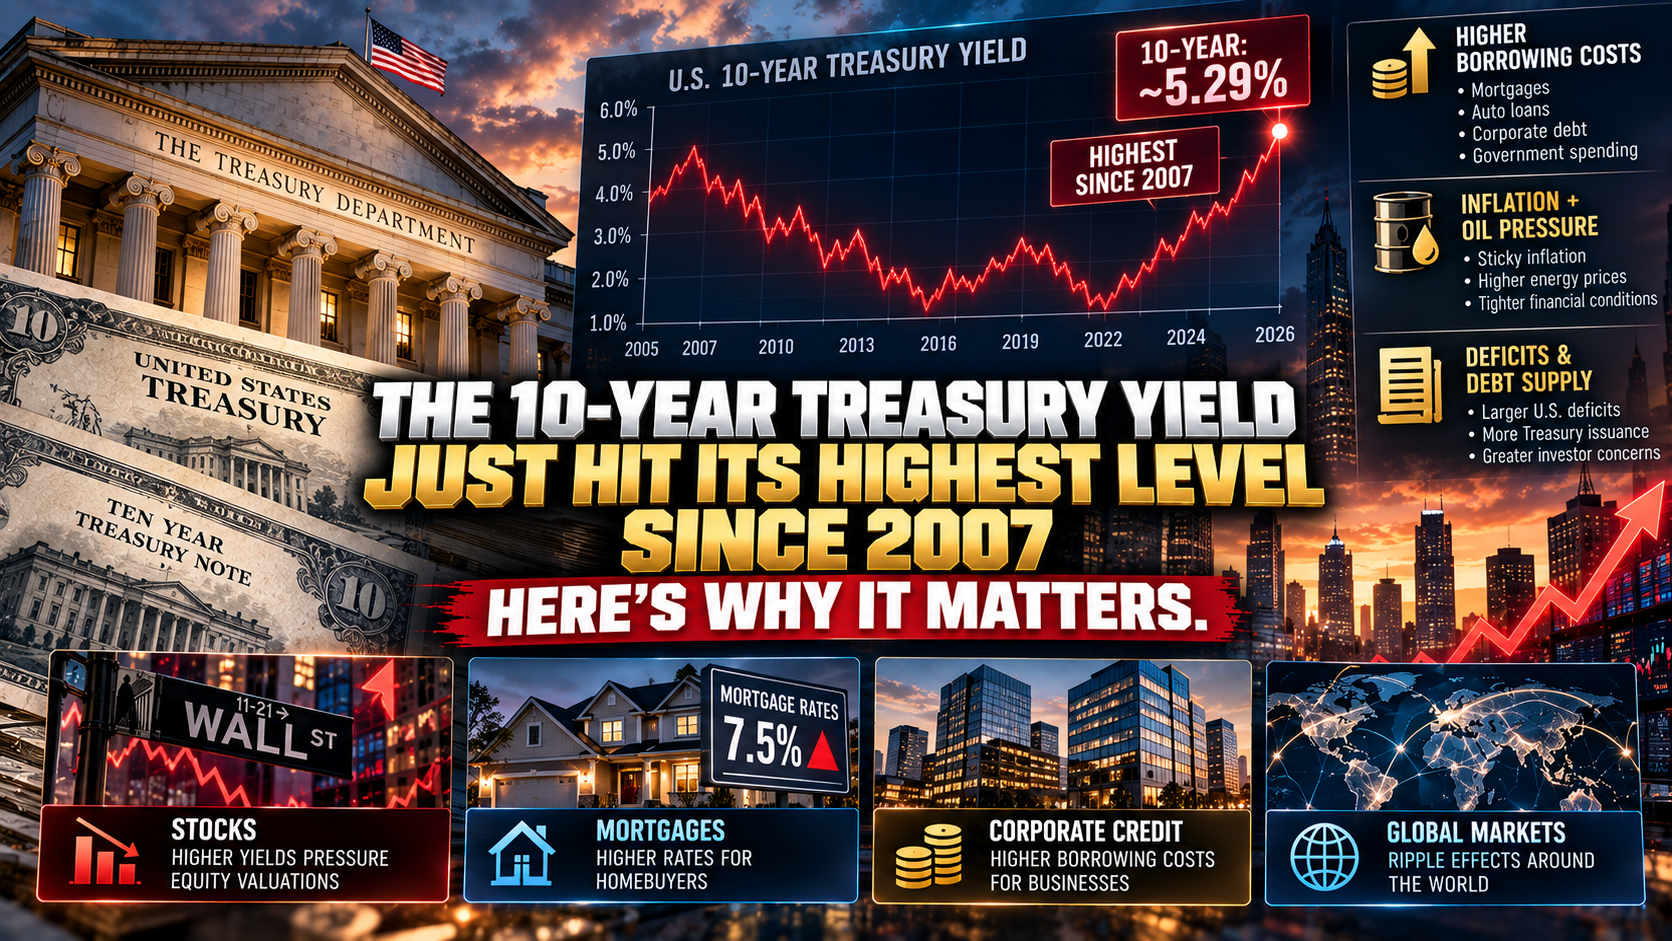
This month, that opportunity cost has soared. The 10-year Treasury yield climbed to 5.21% on Thursday, its highest level since 2007. Short-dated Treasury bills and money market funds are paying rates not seen in almost two decades. For some investors, that makes a non-yielding metal harder to justify.
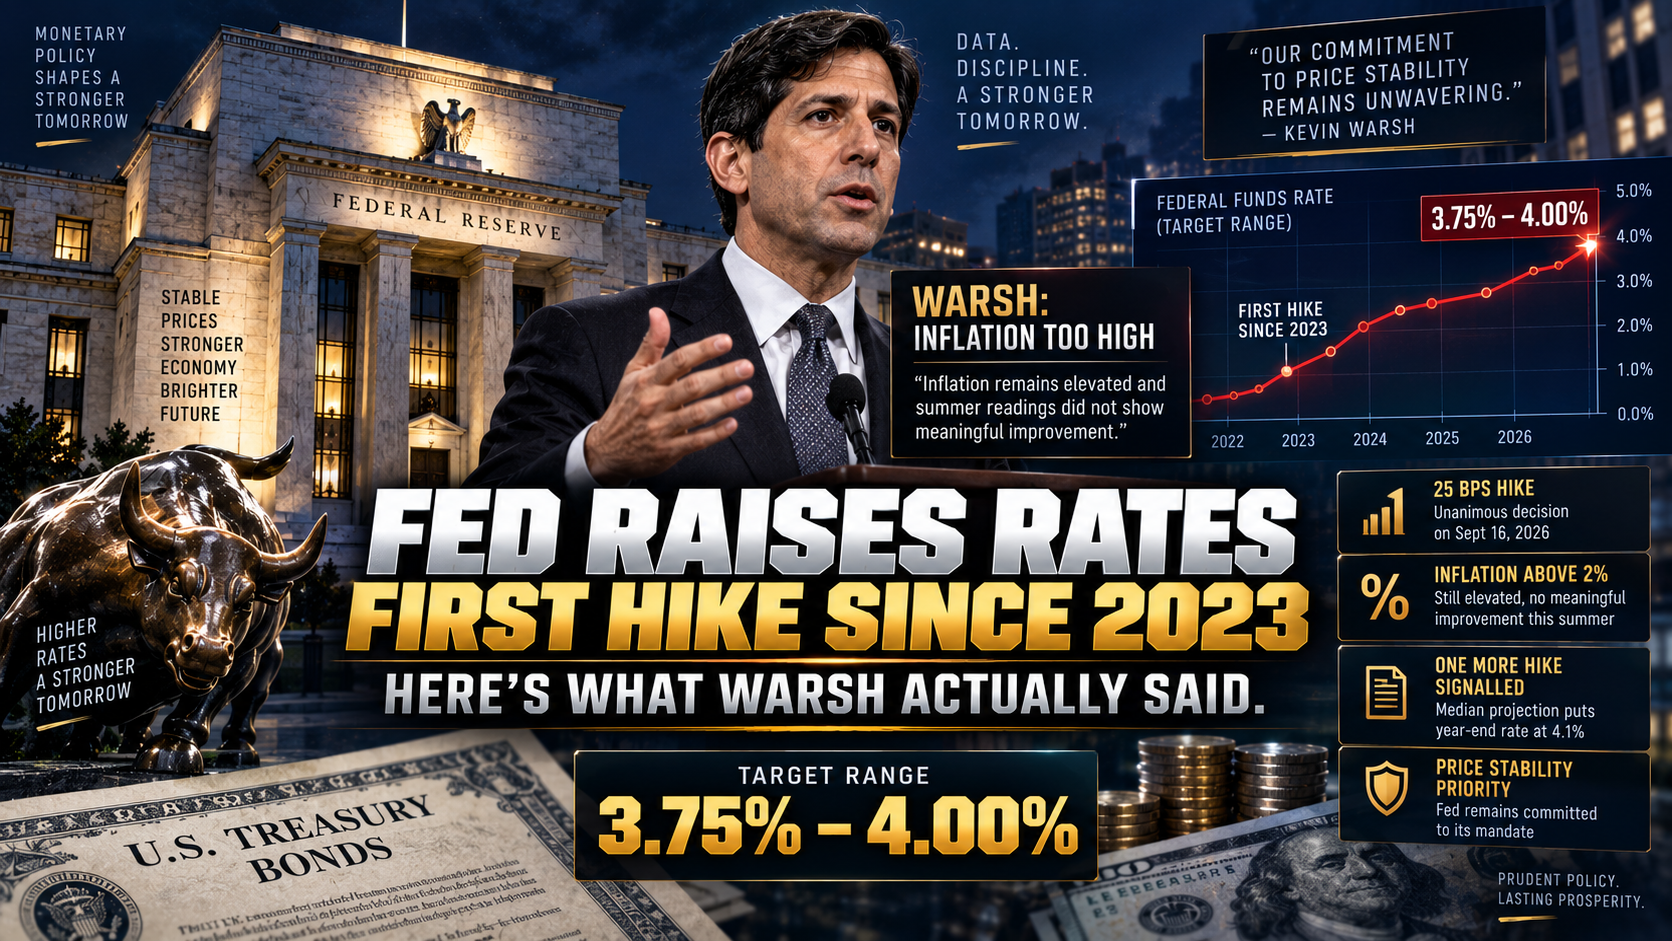
Meanwhile, the Federal Reserve raised interest rates on 16 September for the first time since 2023. Traders are now pricing in a nearly 70% chance of another hike in October and around a 95% probability of an increase by December. Every signal of further tightening strengthens the case for cash over gold.
There is also a currency effect. Gold is priced in dollars, and a stronger dollar makes it more expensive for buyers holding other currencies. Rising US yields have tended to support the dollar, which adds another headwind.
Why gold hasn’t collapsed
If rising yields were the only story, gold would have fallen much further. It has not, and the reason is structural demand that has little to do with interest rates.
Central banks keep buying
The most important buyers in the gold market over the past four years have not been retail investors or hedge funds. They have been central banks.
Central banks purchased 863 tonnes of gold in 2025, according to the World Gold Council. That was slightly below the record pace of more than 1,000 tonnes a year between 2022 and 2024, but still roughly double the pre-2022 annual average.
The shift began after Russia’s foreign reserves were frozen in 2022. That event changed how many emerging-market central banks think about geopolitical risk. Holding reserves in dollars or euros exposes them to sanctions. Holding physical gold in their own vaults does not. Goldman Sachs expects central bank buying to average around 70 tonnes a month, roughly four times the pre-2022 monthly average.
That buying tends to be price-insensitive. Central banks accumulate steadily through rallies and corrections alike, which creates a floor under the market that did not exist a decade ago.
Geopolitical risk remains high
The conflict involving Iran, disruption through the Strait of Hormuz, the war in Ukraine and a US-China relationship that has just been placed on a two-month extension all feed demand for safe-haven assets. Gold has historically benefited when investors worry about systemic shocks, and there is no shortage of potential shocks right now.
Inflation is still elevated
Gold is often described as an inflation hedge. Headline US inflation has been running near 3.4%, well above the Fed’s 2% target, and the Fed’s own projections see personal consumption expenditure inflation at 3.7% this year. Even if rising yields reduce gold’s appeal in the short term, persistent inflation supports its long-term case.
What the big banks are forecasting
Despite the recent pullback, several major institutions remain constructive on gold.
Goldman Sachs Research forecasts gold at $4,900 an ounce by the end of 2026, citing strong central bank demand as reserve managers continue to diversify. The bank has also warned that the growing use of gold derivatives to hedge against large policy changes may be making prices more volatile in both directions.
J.P. Morgan Global Research has been more bullish still, with a forecast earlier this year for prices to average around $6,000 an ounce by the final quarter of 2026. At the same time, its head of base and precious metals acknowledged that investor interest had cooled and described gold as stuck in “a bit of a technical no-man’s land.”
Those forecasts were made before this month’s bond market sell-off, and both look ambitious from today’s level. Reaching $4,900 would require a rise of roughly 14% in about three months. That is possible, but it would probably need a clear turn in Fed policy or a significant geopolitical shock.
How to think about gold in a portfolio
For individual investors, the key question is not where gold goes next week. It is what role, if any, the metal should play in a diversified portfolio.
Gold as insurance. Many financial planners view a modest allocation to gold as protection against extreme scenarios: currency crises, geopolitical shocks or periods when stocks and bonds fall together. That role does not require perfect timing.
Gold as a trade. Buying gold because you expect a short-term price jump is a very different proposition. The past month demonstrates how quickly sentiment can shift when interest rates move.
The cost of holding it. Physical gold involves storage and insurance costs. Exchange-traded funds are cheaper and more convenient, but still carry fees. Mining stocks behave differently from the metal itself and carry company-specific risk.
The opportunity cost is real. With Treasury bills yielding far more than they did two years ago, holding gold now means giving up a meaningful guaranteed return. That trade-off did not exist when rates were near zero.
What to watch next
Three factors are likely to decide gold’s direction over the coming weeks.
- Bond yields. A retreat in the 10-year yield from 5.2% would ease the pressure on gold quickly. A push higher would add to it.
- Fed expectations. Wednesday’s PCE inflation data and Friday’s September jobs report will shape the odds of an October hike. A softer reading would likely lift gold.
- Geopolitics. Progress on reopening the Strait of Hormuz would lower oil and inflation expectations, which could cut both ways: good for yields, less supportive for safe-haven demand.
Gold’s volatile 2026 in four moves
It helps to see how quickly the story has changed this year.
January: Gold surges to a record above $5,500 an ounce, capping a rally that added nearly 65% in 2025.
Spring and early summer: Prices pull back sharply from the peak as investors take profits and interest rate expectations shift. By mid-July, gold has fallen well below its highs.
August: A renewed rally lifts the metal about 15% from its July low to around $4,600 by late August, prompting upbeat year-end forecasts from major banks.
September: The bond market sell-off and the Fed’s first hike since 2023 push gold back towards $4,280, leaving it down more than 6% for the month.
The bottom line
The gold price today reflects a tug-of-war between two powerful forces. Record-high bond yields and a tightening Fed are pushing it down. Relentless central bank buying, persistent inflation and elevated geopolitical risk are holding it up.
At around $4,280, gold is more than 20% below its January peak but still well above where it traded a year ago. Whether this is a pause in a long-term bull market or the start of a deeper correction will depend largely on what happens to interest rates. For now, the metal is doing what it has done for centuries: waiting for the next crisis.
This article is for general information only and does not constitute financial or investment advice.