


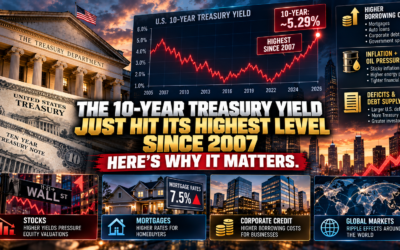
The 10-Year Treasury Yield Just Hit Its Highest Level Since 2007. Here’s Why It Matters.
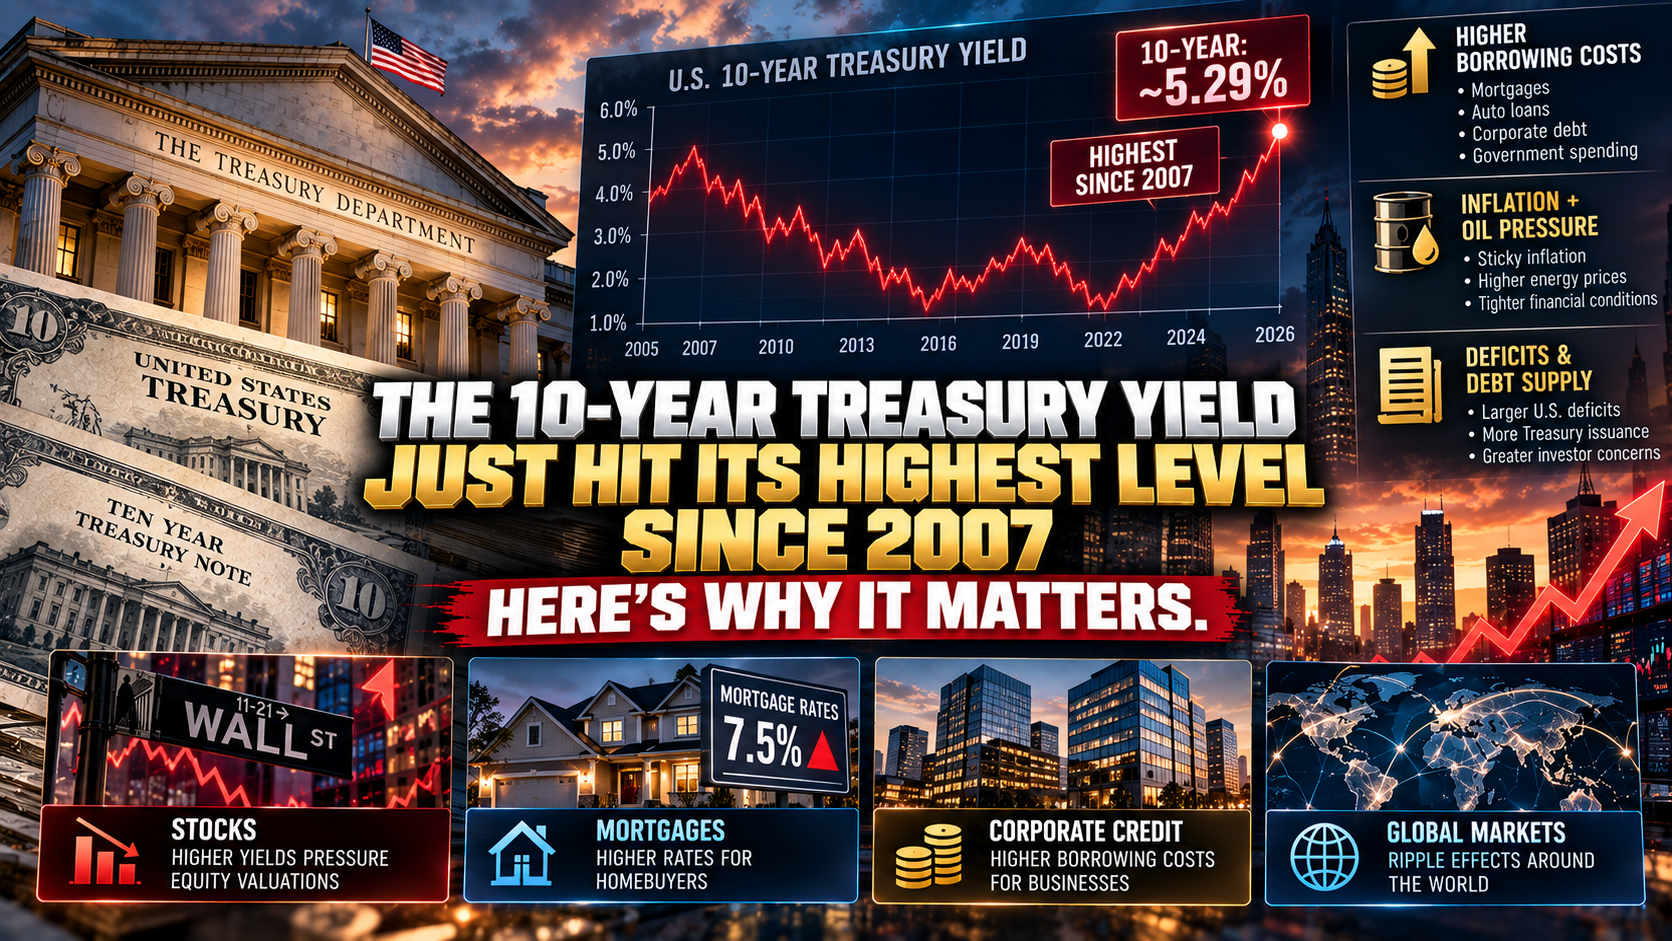
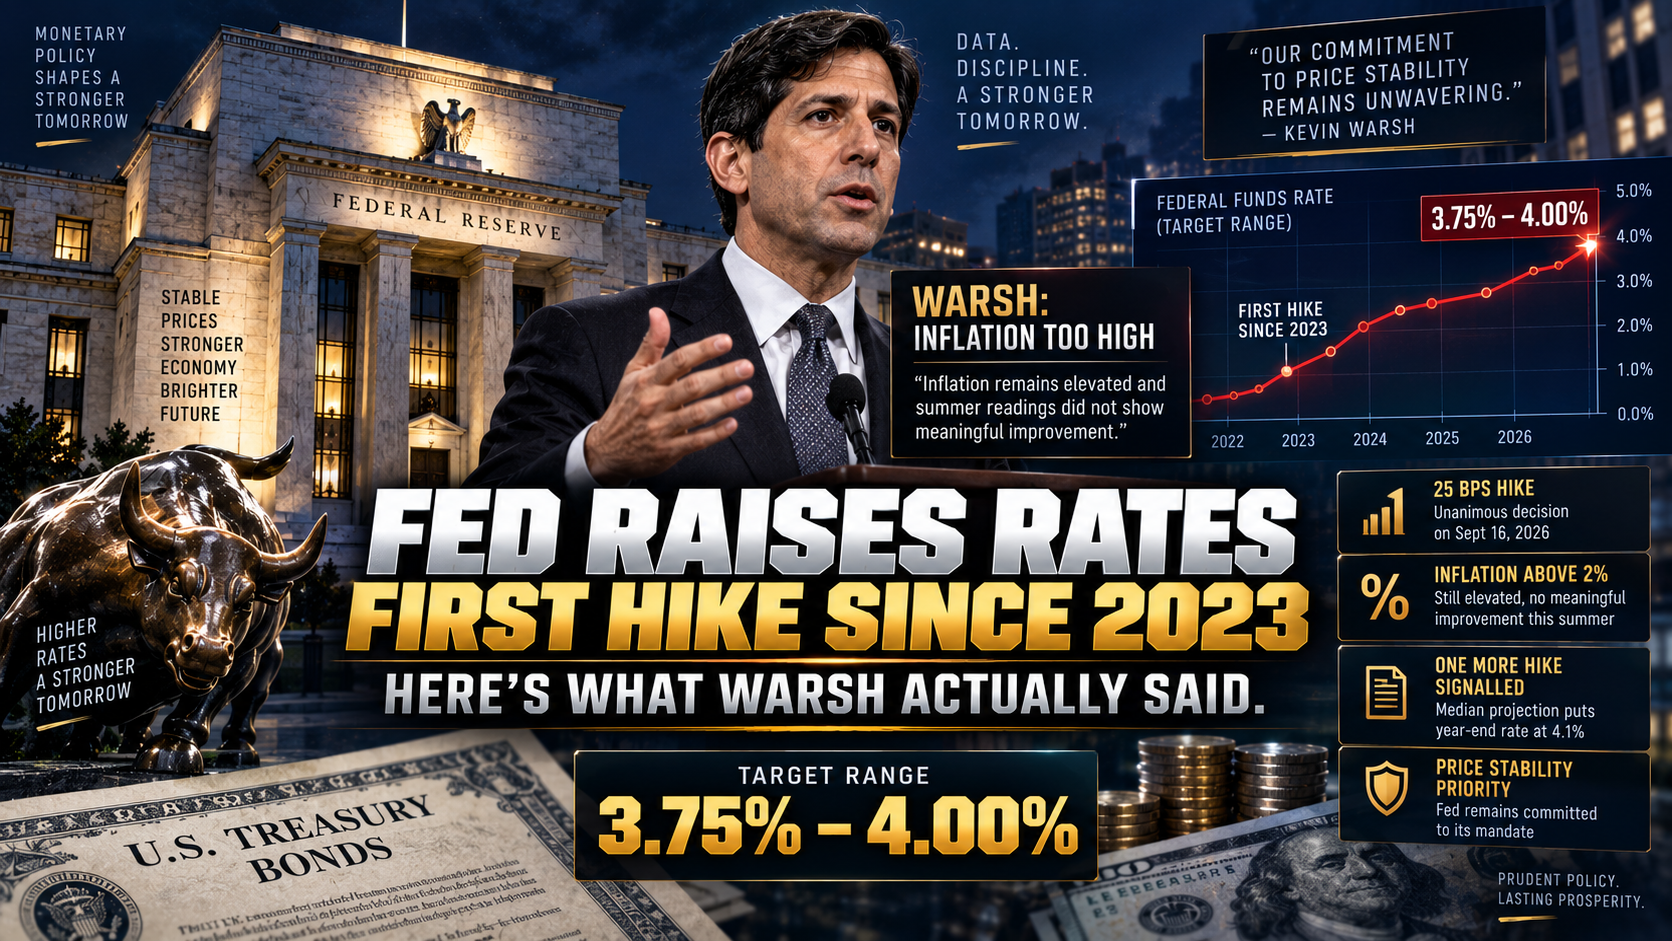
The last time the 10-year Treasury yield traded where it does today, the iPhone was a few weeks old, Lehman Brothers still existed and the global financial crisis had not yet begun. That was July 2007. On Thursday, the benchmark yield climbed 10 basis points to 5.21%. The 30-year bond pushed to just shy of 5.5%, its highest level since 2004. The five-year note breached 5% for the first time since 2007 the day before. The 10-year Treasury yield is arguably the most important interest rate in the world. It sets the price of mortgages, car loans, corporate borrowing and government debt far beyond American borders. When it moves this fast, it rewrites the cost of almost everything that involves borrowing money. How fast the 10-year Treasury yield has climbed The speed of this move is what has unsettled investors. In early September, the yield was still sitting just below 5%. Then, on 15 September, the day before the Federal Reserve’s policy decision, it reached 5.041%, the highest level since July 2007, as oil prices surged on the Iran conflict and traders braced for a rate hike. The Fed duly raised rates the following day, lifting its benchmark to a range of 3.75% to 4%, the first increase since 2023. Rather than calming the bond market, the hike seemed to intensify selling. On Wednesday, 23 September, the 10-year jumped 16 basis points to 5.12% in a single session. Robust economic data and a weak Treasury auction combined with rising oil prices to push yields across most maturities to their highest levels in almost two decades. Thursday then added another 10 basis points. A move of that size across a few days would be notable in any market. In the world’s deepest and most liquid bond market, it is exceptional. Why yields are rising: the four pressures Wall Street does not agree on a single explanation, and that disagreement is itself part of the problem. Four forces are pushing in the same direction at once. 1. Inflation driven by energy The war involving Iran has disrupted oil supply through the Strait of Hormuz for months. Energy prices feed directly into inflation, and inflation erodes the real value of fixed bond payments. Investors therefore demand higher yields to compensate. Every time crude has spiked this month, Treasuries have sold off in response. 2. A more hawkish Federal Reserve Chairman Kevin Warsh has repeatedly described inflation as “a choice,” signalling that the Fed intends to keep tightening until prices come down. This week, Fed governor Michael Barr added that additional rate hikes are needed to bring down sticky inflation. Traders raised bets on another hike in October to around 70%, and markets are pricing roughly a 95% chance of an increase by December. 3. A flood of bond supply Governments are borrowing heavily, and so are corporations. The build-out of artificial intelligence infrastructure has driven a wave of corporate debt issuance, adding to the supply of bonds competing for investor money. More supply, with no matching rise in demand, pushes prices down and yields up. The weak auction on Wednesday was a reminder that buyers are becoming more selective. 4. Concern about the deficit Mounting government debt means investors increasingly demand extra compensation for holding long-dated Treasuries. That “term premium” has been rising, particularly at the long end of the curve, which explains why the 30-year bond has moved even more dramatically than shorter maturities. What the 10-year Treasury yield means for your money This is not an abstract market story. The 10-year yield feeds directly into the borrowing costs of ordinary households. Mortgages. Home loan rates track the 10-year closely. Freddie Mac’s weekly survey showed the average 30-year fixed mortgage rising to 7.03% this week, the first reading above 7% since January 2025. A year ago it was 6.30%. Car loans and personal credit. Auto lenders and personal loan providers price off Treasury yields. Expect higher quoted rates on new financing. Savings and cash. There is an upside. High-yield savings accounts, money market funds and short-dated Treasury bills pay significantly more than they did a year ago. For savers, this is the most attractive environment in nearly two decades. Retirement portfolios. When yields rise, existing bond prices fall. Anyone holding bond funds has seen paper losses this month, although new money invested today locks in much higher income. The stock market’s surprising resilience Given all of this, the equity market has held up remarkably well. The S&P 500 finished Friday at 7,743.41, up 0.51% on the day, while the Dow rose 0.93% to 51,828.62 and the Nasdaq Composite gained about 0.5%. That closed out the S&P 500’s first winning week in three, and the index remains close to the all-time high it set last month. Analysts at Charles Schwab offered one explanation: the climb in yields has been relatively orderly, inflation is only slightly high and economic conditions have not deteriorated. Falling oil prices also helped on Friday, with Brent dropping to around $97 a barrel on hopes that the Strait of Hormuz could reopen. However, the prospect that higher interest rates are here to stay is unnerving investors who fear that eventually something has to break. Higher yields raise the discount rate applied to future company earnings, which weighs most heavily on expensive growth stocks. They also make bonds a more attractive alternative to equities for the first time in years. Is 5% a ceiling or a floor? Five percent is more than a round number. It is the level at which financing homes, companies and the federal government moves into a range last seen before the 2008 crisis. The bull case for bonds is that yields have overshot. If oil continues to fall on Middle East diplomacy and inflation data cools, the Fed could pause after one more hike, and yields could retreat quickly. Buyers who lock in 5% now would benefit. The bear case is that this is a structural reset rather than a spike. Persistent deficits, heavy…